

Starlink India’s latest response to Reliance Industries has put the spotlight on a question larger than a public exchange between two powerful companies: what does it actually take to launch satellite internet services in India? Elon Musk’s company says it has spent five years working with regulators, the telecommunications industry and operators, and has built the network systems, gateways and other infrastructure needed to handle Indian customers’ internet traffic. Yet commercial service still depends on a regulatory chain that extends beyond a licence.
That distinction is central to understanding India’s satellite internet market. A company may receive a satellite communication licence and still be unable to begin selling services until spectrum allocation, security conditions and other operational requirements are completed. The current contest involving Starlink, Reliance’s Jio Satcom and Bharti Airtel-backed Eutelsat OneWeb is therefore not only a race between technology companies. It is also a test of how India will manage a new layer of connectivity infrastructure.
Starlink’s response came after Reliance said it welcomed competition in satellite communication but expected every company operating in India to follow Indian laws and policies. In its post on X, Starlink said it had been working for five years with Indian regulators, the telecommunications industry and operators. The company also said it had built special network systems, gateways and other infrastructure in India, with the required government approvals, to securely manage Indian customers’ traffic.
The claims were made against the backdrop of a wider dispute. Musk had recently alleged on social media that influential business groups were trying to obstruct Starlink’s entry into India and seeking to preserve their dominance over Indian customers. He also questioned the influence of business groups on decision-making in India. The central government rejected those allegations and said India’s regulatory system did not discriminate against any company. It said satellite operators would have to meet security, spectrum and other regulatory conditions.
Reliance’s response framed the issue as a competition question. The company said it had never been afraid of competition and welcomed Starlink and other companies in satellite communication. It cited Jio’s entry into the Indian telecom market in 2016, when the company had no customers, and said it now had more than 530 million customers. Reliance argued that competition should ultimately be judged by which company delivers better services to customers. At the same time, it said openness to investment and new technology had to operate within the rule of law.
The company also made clear that Jio’s own satellite internet service was waiting for the necessary approvals. That detail is important because it shows that the regulatory delay is not simply a barrier faced by an overseas entrant. The same sequence of permissions affects domestic and foreign operators, although companies may differ in the stage of infrastructure preparation they have reached.
## Why a licence is not the same as a launch
According to the report, Communications Minister Jyotiraditya Scindia has said that Starlink, Jio Satcom and Eutelsat OneWeb have received satellite communication licences. Amazon’s Project Kuiper has also shown interest but would need to follow the prescribed process. The report does not establish that all licensed operators have received final approval to begin commercial services.
The difference between licensing and commercial operation reflects the layered nature of telecom infrastructure. A licence establishes that a company has met a particular regulatory threshold. It does not by itself settle how spectrum will be assigned, what security conditions will apply, how networks will connect with domestic systems or what fees will be charged for spectrum use.
For satellite internet, spectrum is a particularly important part of the market structure. The government is working to finalise a revenue-based fee system for spectrum, while the Telecom Regulatory Authority of India and the Department of Telecommunications are involved in the process. Until those rules and allocations are settled, operators can have satellites, ground infrastructure and market plans without being able to provide ordinary customers with a commercial service.
This is why the current debate cannot be reduced to whether Starlink has already built enough infrastructure. Infrastructure readiness is one part of market entry. The other parts are the authorisation to use spectrum, compliance with security requirements and completion of the procedures that allow the service to operate within India’s communications framework.
## The infrastructure race is happening on the ground as well as in orbit
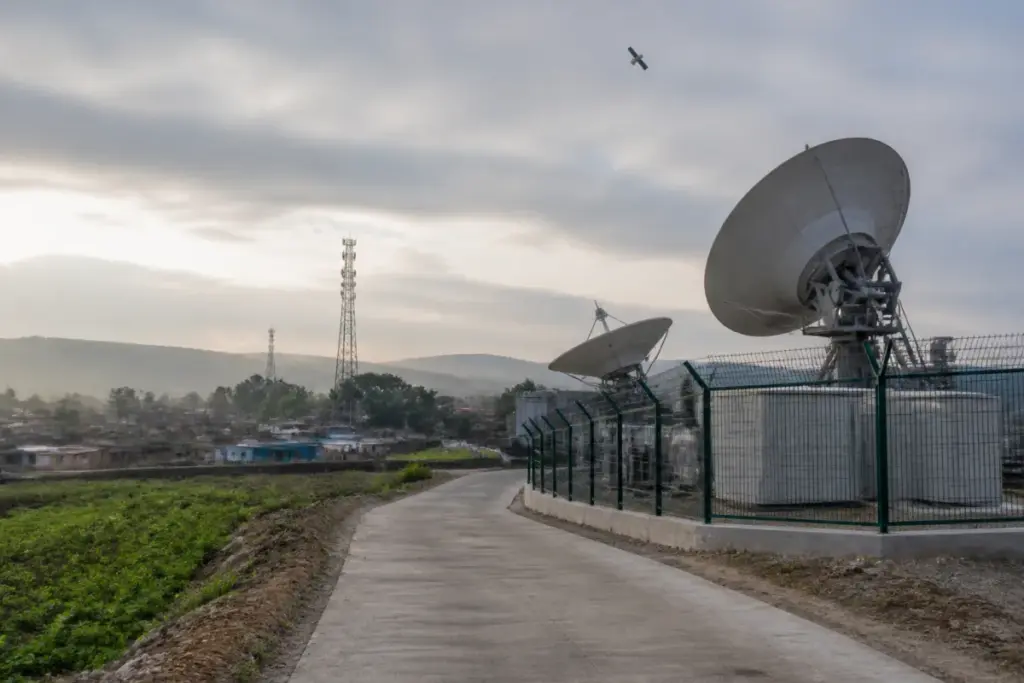
Starlink’s statement focuses on the physical and technical systems it says it has built in India. Its reference to gateways and domestic network systems points to a requirement that satellite connectivity is not simply a signal travelling between a satellite and a user terminal. Customer traffic needs to be handled through systems connected to the country in which the service is being provided.
That ground layer gives the regulatory debate a direct urban and infrastructure dimension. India’s internet network is usually discussed through mobile towers, fibre routes and data infrastructure. Satellite systems add another layer, particularly for places where towers or fibre networks are difficult or expensive to build. But satellite connectivity still requires terrestrial facilities, approvals and operating rules. The result is a hybrid infrastructure model rather than a replacement for existing networks.
OneWeb’s experience, as described by Bharti Enterprises chairman Sunil Mittal, illustrates the gap between preparation and permission. Mittal said at the Bloomberg New Economy Forum that his company had applied around five years earlier, that its ground network had been ready for three years and that its satellites had been over India for five years. Despite that preparation, he said the company was still waiting for permission to begin commercial services.
Mittal’s account also complicates the claim that Starlink is uniquely being held back. It suggests that multiple operators have spent years preparing networks while waiting for the regulatory conditions required for commercial launch. The supplied report does not independently establish the status of each company’s approvals, but the competing statements point to a common issue: the timetable for satellite internet depends on public processes as much as on private investment.
## Rural connectivity is the main public-interest promise
Reliance is reportedly working on a plan involving around 1,600 low Earth orbit satellites, with the aim of extending internet connectivity to approximately 600,000 villages. Low Earth orbit satellites operate relatively close to Earth and can support connectivity in areas where mobile towers or fibre networks are difficult or costly to deploy.
That proposed scale gives the satellite internet contest significance beyond corporate rivalry. If the technology is deployed effectively, it could add an option for communities that remain difficult to connect through conventional infrastructure. However, the report does not provide details on pricing, coverage schedules, user terminals, service quality or the number of villages that would be reached first. Those factors will determine whether satellite internet becomes a broad public utility or remains a specialised service for locations and customers that can bear its costs.
The same distinction applies to the claims of high-speed service. A company’s ability to provide high-speed connectivity depends not only on satellites in orbit but also on ground infrastructure, spectrum access, network design, customer equipment and regulatory clearance. Without those elements working together, the promise of coverage cannot be treated as evidence of an operating service.
## India is setting the rules while the market is forming
The government’s position, as reported, is that the regulatory system is neutral but that every operator must meet security, spectrum and other conditions. That approach places the state at the centre of market formation. It must create a framework that permits new connectivity technologies while determining how scarce spectrum is allocated, how fees are structured and how communications security is enforced.
The sequence matters for competition. If rules are finalised only after companies have built infrastructure, operators may face uncertainty about the cost and timing of launch. If the framework is designed without accounting for the technical differences between satellite and terrestrial networks, it may also affect how widely services can be deployed. The supplied material does not establish which final spectrum model will be adopted or when commercial approvals will be granted.
For companies, that uncertainty is now part of the competitive landscape. Starlink is emphasising years of preparation and domestic infrastructure. Reliance is emphasising competition under Indian law and its own scale in telecom. OneWeb is pointing to its earlier application and long-standing ground network. These claims are not merely public relations positions; they are arguments about how readiness and priority should be understood in a market where final permission remains decisive.
The larger urban question is whether India can use satellite connectivity to close gaps left by conventional infrastructure without treating it as a substitute for fibre, mobile networks or accountable public regulation. Satellite systems may be particularly valuable for remote and difficult-to-serve areas, but their public benefit will depend on affordability, reliability and integration with the wider digital network.
The evidence currently confirms that Starlink, Jio Satcom and OneWeb are competing for entry into India’s satellite communication market, while the government continues to work through spectrum and other regulatory requirements. It also shows that network preparation and licensing do not automatically equal commercial launch. The next decisive developments will be the final spectrum framework, completion of security and operational conditions, and the permissions that allow licensed operators to begin serving customers.


