The Jio Platforms IPO has opened with exceptionally strong institutional demand, but its larger significance extends beyond a successful share sale. The offering places a market value on one of India’s most important digital infrastructure businesses and shows how telecom networks, broadband access, cloud-linked services and financial capital are becoming increasingly connected in the country’s urban economy.
According to Aaj Tak Business, the ₹30,213-crore issue was fully subscribed within the first 100 minutes of opening on 21 October. Qualified institutional buyers placed bids worth more than three times the shares reserved for them. The report also said that the anchor book attracted bids exceeding the available allocation, with Jio raising approximately ₹8,110 crore from anchor investors at the upper price of ₹1,119 a share.
The reported demand came from both global and domestic institutions. Fidelity, Allianz, BlackRock and the Abu Dhabi Investment Authority were named among the international participants, while SBI and HDFC mutual funds were cited among domestic investors. Capital Group was also reported to have participated. These investors’ involvement indicates strong institutional attention, although anchor demand does not guarantee how the stock will perform after listing.
The structure of the issue is central to understanding its significance. The report describes it as a 100 per cent fresh issue, with no share sale by early investors such as Meta and Google or by members of the Ambani family. A large portion of the approximately ₹27,500 crore expected to be raised is intended for repaying debt held by Reliance Jio Infocomm.
That use of proceeds makes the IPO more than a liquidity event for existing shareholders. It is also a balance-sheet transaction. If the reported debt repayment proceeds as planned, the telecommunications business would move closer to a net-debt-free position. In operational terms, lower debt servicing obligations could allow a larger share of earnings to translate into free cash flow. The supplied report, however, does not establish the precise post-issue debt position or the time required to reach that state.
This distinction matters because telecom is a capital-intensive industry. Network expansion, spectrum costs, fibre deployment, data centres, customer equipment and maintenance require sustained investment. A company can have a large subscriber base and substantial revenue while still needing significant capital to maintain service quality and expand capacity. Using IPO proceeds to reduce debt therefore changes the financial structure supporting the network, not merely the ownership structure of the company.
The reported valuation also places Jio in direct comparison with Bharti Airtel. At the upper end of the price band, Jio Platforms is valued at roughly 33 to 34 times its reported FY26 earnings, compared with approximately 39 to 40 times for Bharti Airtel. The article cited comments by Kotak Mahindra Bank founder Uday Kotak, who described the company as difficult to replicate and considered the upper price band attractive relative to peer valuations. Brokerage firms including Emkay, Motilal Oswal and Anand Rathi were also reported to have recommended subscribing, citing valuation, market leadership and potential growth avenues.
Those comparisons frame Jio primarily as a listed financial asset. Its urban importance, however, comes from the infrastructure embedded in the business. The report says Jio has more than 53.3 crore customers and handles over 60 per cent of India’s data traffic. It also points to the company’s 4G and 5G technology stack, nationwide coverage and expanding AirFiber fixed-wireless access base.
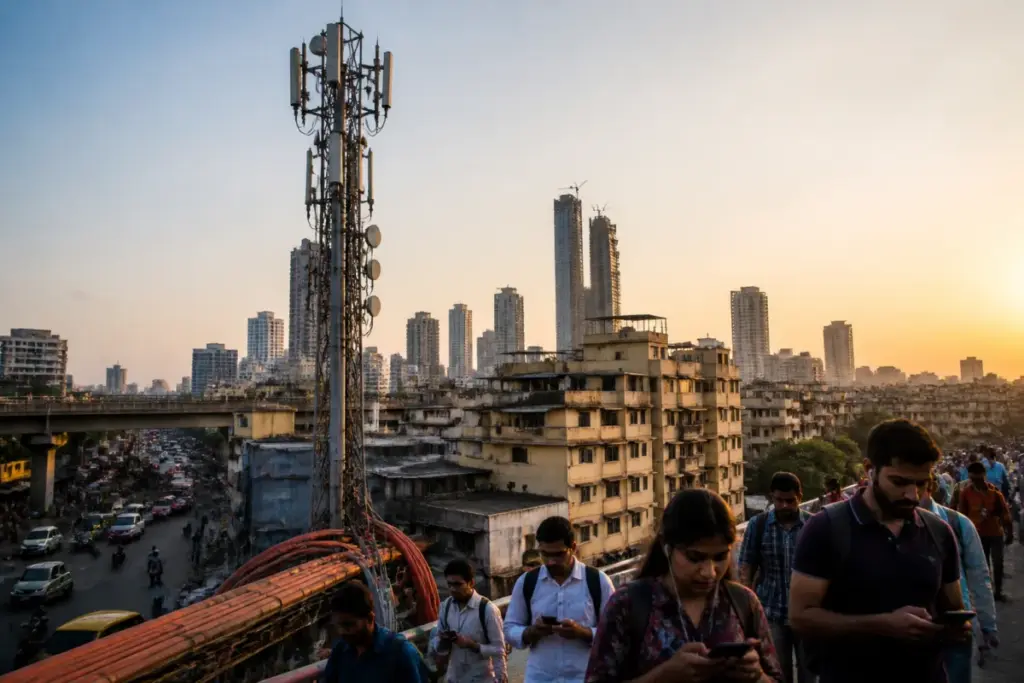
These figures describe a network with national reach, but they also reveal the scale at which digital connectivity now operates as an urban utility. Mobile data supports payments, education, commerce, logistics, public communication, work and entertainment. Broadband access increasingly affects whether households can participate in digital services, while businesses depend on reliable connectivity for daily operations. In this environment, telecom networks are not separate from the built environment. They run through towers, fibre routes, exchanges, data facilities, homes and commercial premises.
Jio’s fixed-wireless broadband expansion is especially relevant to the question of last-mile access. Fibre remains important, but laying physical networks can be difficult in dense neighbourhoods, informal settlements, older buildings and areas where road cutting and permissions are complicated. Fixed-wireless services can provide another route to household connectivity. The supplied report does not provide city-level AirFiber adoption, speeds or affordability data, so it cannot establish how evenly this infrastructure is reaching different income groups or locations.
The company’s market position also raises an institutional question: how should India balance the benefits of scale with the risks that accompany concentration? A large network can reduce unit costs, accelerate technology deployment and create an integrated platform for digital services. At the same time, the dependence of consumers and businesses on a small number of major networks makes competition, service reliability and regulatory oversight important parts of the infrastructure debate. The source material does not provide market-share comparisons beyond the reported data-traffic figure, so the broader competitive effect requires separate examination.
The IPO also changes the way the market may view Reliance Industries. The report says that a separate listing could make Jio’s value more transparent and potentially reduce the holding-company discount applied to Reliance Industries shares. This is a corporate-structure issue with consequences for investors, but it also affects how capital may be allocated across the wider Reliance ecosystem. A separately valued digital infrastructure company can make its earnings, debt, investment requirements and growth expectations easier for public-market participants to assess.
The historical significance of the offering is similarly tied to public participation in capital markets. The report describes it as the group’s first major listing in nearly two decades and compares its importance with Dhirubhai Ambani’s 1977 public issue, which helped bring many Indian investors into the stock market. The comparison is historical rather than operational, but it places the Jio issue within a longer story of large Indian businesses using public markets to build a broad shareholder base.
The immediate subscription figures should nevertheless be read carefully. The issue was scheduled to remain open until 23 October, and the supplied report noted that retail and non-institutional bidding often increases closer to the closing date. The first-day response therefore provides evidence of strong early demand, not the final subscription outcome. Nor does institutional participation establish future listing performance, service quality or the eventual returns available to shareholders.
What the Jio Platforms IPO confirms is that digital connectivity has become a major destination for institutional capital in India. The offering links household access, telecom infrastructure, technology ownership and corporate finance in a single transaction. What remains unclear from the available material is how the proposed debt reduction will affect future network investment, whether the company’s growth will be evenly distributed across regions and income groups, and how its market position will evolve as competitors expand their own 5G and broadband networks.
The next concrete milestone is the close of the issue on 23 October, after which the final subscription pattern and subsequent listing process will provide a fuller test of the market’s assessment of Jio Platforms. Until then, the strongest evidence is the scale of early institutional demand and the stated plan to use much of the fresh capital to strengthen the balance sheet behind one of India’s largest connectivity networks.