

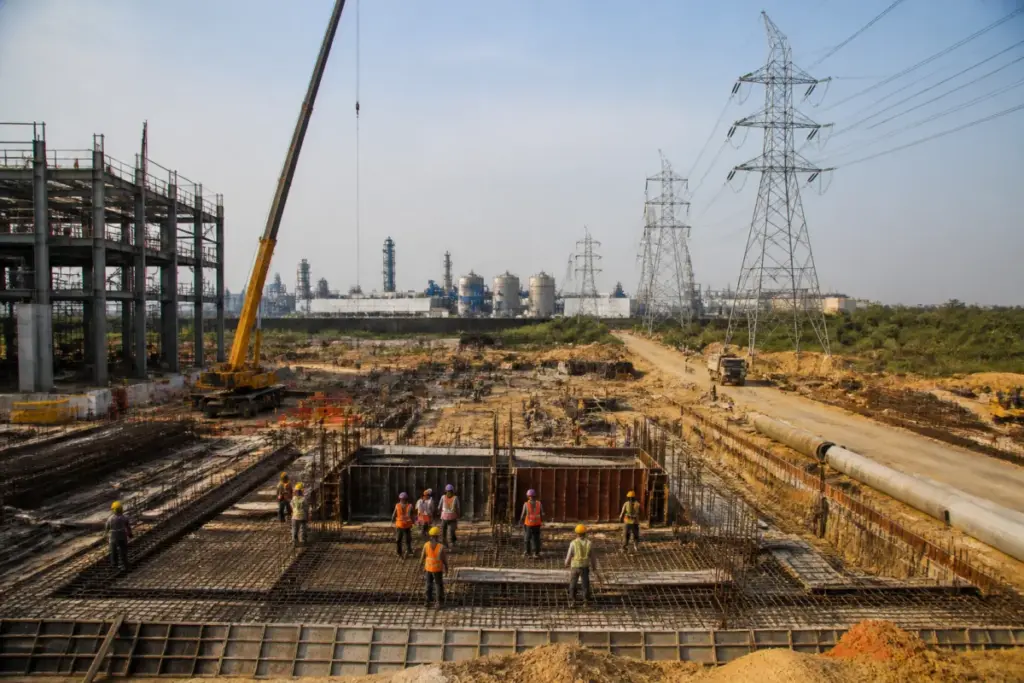
India’s private capex pipeline has reached Rs 99.7 lakh crore, but the scale of announced investment hides a more uneven reality: project costs have surged far faster than the number of projects, while much of the latest growth is concentrated in a handful of sectors and states. The findings, published by Union Bank of India Research, present the investment cycle as significant but not yet broad-based.
The pipeline expanded 39% over the year to September 2026 and has grown 87% in two years. Yet the number of projects increased by only 18% during the same period. That gap matters because it indicates that the rise in planned spending has been driven primarily by larger projects rather than by a widespread increase in investment activity across companies, sectors and locations.
The distinction between an announced pipeline and executed investment is central to understanding the figures. The Rs 99.7 lakh crore represents planned private-sector investments, not projects that have necessarily reached construction, financing closure, commissioning or operation. UBI Research therefore treats the pipeline as an opportunity for lenders while also cautioning that project execution, financing requirements and supporting infrastructure must be assessed before loans are sanctioned.
The report said the capex cycle is “firmly aligned with Viksit Bharat 2047 aspirations”, but also cautioned that the recovery was not yet broad-based. The evidence behind that caution lies in the composition of the pipeline. Announced project costs increased by Rs 46.4 lakh crore over the past two years. In comparison, only Rs 7 lakh crore was added in the eight years up to March 2022. The overall pipeline is now 4.1 times its March 2014 level.
That acceleration signals a substantial change in the scale of private investment being planned. It does not, however, establish that investment is spreading evenly through the economy. A smaller number of very large projects can increase the total value sharply without producing a comparable rise in the number of industrial sites, construction locations, employers or local supply chains. The project-count data in the report is therefore as important as the headline value of the pipeline.
Sectoral concentration is especially pronounced. Information technology-enabled services and conventional power together accounted for 87% of the latest annual increase. IT-enabled services added Rs 16.8 lakh crore to the pipeline, while conventional power contributed Rs 7.6 lakh crore.
The IT-enabled services pipeline rose from Rs 2.2 lakh crore to Rs 18.9 lakh crore in a year and covered 160 projects. That sharp increase made services the fastest-growing segment, with annual growth of 347% to Rs 21.9 lakh crore. The figures show how quickly a sector can alter the national investment picture when large planned projects are added, even when the wider project base does not expand at the same rate.
Looking at the outstanding pipeline rather than only the annual increase, manufacturing and electricity together accounted for 74% of the total. Manufacturing projects represented Rs 41.3 lakh crore, while electricity projects stood at Rs 32.2 lakh crore. These figures place industrial capacity and power supply at the centre of the private investment cycle.
For cities and regions, the location of investment is as significant as its sectoral composition. Maharashtra remained the leading destination for announced private investments, with projects worth Rs 28.6 lakh crore, or around 29% of the total pipeline. The distribution of new additions was even more concentrated: Maharashtra, Andhra Pradesh, Telangana, Odisha and Uttar Pradesh together accounted for 94% of the pipeline’s annual increase.
This concentration creates two distinct administrative questions. The first is whether the states receiving the largest announcements have the land, power, transport links, water supply and other urban services needed to support them. The second is whether regions outside the leading group are participating in the investment recovery at all. The UBI report flags concentration as a risk, but the supplied findings do not establish how many projects have secured land, obtained approvals or begun construction in each state.
The state-level distribution also has implications for the built environment. Large industrial, power and services projects require more than a project site. They can generate demand for worker housing, roads, logistics facilities, electricity networks and municipal services. However, the report does not provide a project-by-project assessment of these requirements or indicate whether host cities and local authorities have planned for them. That gap is important because announced investment can move faster than the public infrastructure needed to make it operational.
The most direct infrastructure warning in the report concerns electricity. Planned investment in power generation stood at Rs 32 lakh crore, while planned transmission investment amounted to only Rs 0.17 lakh crore. This is a substantial difference between the capacity intended to produce electricity and the network planned to move it.
Power generation and transmission are institutionally connected but financially and operationally distinct parts of the electricity system. A generation project may be announced, financed and constructed, yet still face constraints if the transmission system cannot evacuate its output. UBI Research therefore called on banks to examine power evacuation arrangements carefully before sanctioning loans.
The generation-transmission gap illustrates why the value of a private capex pipeline cannot be assessed through project announcements alone. The viability of large investments depends on linked systems: transmission capacity, access to land and utilities, financing, approvals and the ability of public agencies and private developers to complete supporting works. A high pipeline value can coexist with execution bottlenecks if these links are not developed at the same pace.
For lenders, this changes the nature of the opportunity. A larger pipeline can create demand for project finance and related credit, but the report warns that the scale of announced investments is not sufficient evidence of bankability. Financing decisions need to consider execution prospects, funding requirements and power evacuation arrangements. The report’s emphasis is therefore not simply on expanding credit, but on distinguishing credible projects from proposals that remain vulnerable to infrastructure or implementation constraints.
For policymakers, the figures point to a coordination challenge. Private investment is being announced through projects that may fall under different sectors, state jurisdictions and infrastructure systems. Manufacturing, electricity and IT-enabled services do not require identical forms of public support, but each depends on timely decisions relating to land, approvals, connectivity and utilities. The available material does not specify the institutional mechanism being used to coordinate these requirements, but the concentration of investment increases the importance of such coordination.
The data also complicates the idea of a broad-based investment revival. The pipeline is larger than it was in March 2014, and its two-year expansion is much greater than the increase recorded in the eight years up to March 2022. At the same time, project numbers have grown by only 18% against an 87% rise in pipeline value over two years. The recovery is therefore strong in aggregate terms but narrower when measured by the spread of projects.
That distinction affects how the investment cycle may be experienced on the ground. A few high-value projects can produce significant construction activity and infrastructure demand in selected locations, while leaving other regions with limited new investment. Similarly, large projects may create substantial requirements for power, transport and services without necessarily producing a proportional number of projects across smaller firms or districts. The supplied report does not quantify employment, local procurement or household-level effects, so those outcomes cannot be inferred from the pipeline value alone.
The central urban question is whether India’s investment geography can be matched by an equally coordinated geography of infrastructure. Maharashtra, Andhra Pradesh, Telangana, Odisha and Uttar Pradesh account for most of the annual increase, while manufacturing and electricity make up most of the outstanding pipeline. This places pressure on the public systems surrounding private projects and on the institutions responsible for approving, financing and connecting them.
The UBI Research findings confirm that India’s planned private investment pipeline is expanding rapidly and that the increase is concentrated in large projects, selected sectors and a small group of states. They also show why the next measure of progress cannot be announcements alone. The critical indicators will be project execution, financing closure, supporting infrastructure and the ability of power networks to evacuate planned generation. Until those links are demonstrated, the pipeline represents substantial potential rather than completed investment.


